Does Car Insurance Cover Tires And What You Should Expect
Does car insurance cover tires? The answer depends on your policy type and the cause of damage. Comprehensive coverage may help with tire damage from theft, vandalism, or weather events, while collision coverage can apply if tires are damaged in an accident. Standard policies often exclude normal wear and tear, so understanding your auto insurance policy details is essential before filing a claim.
Many drivers assume their car insurance covers everything that happens to their vehicle. But when a tire gets damaged, the question becomes tricky. Does car insurance cover tires? The short answer is: it depends. Your coverage type, the cause of damage, and your specific policy all play a role.
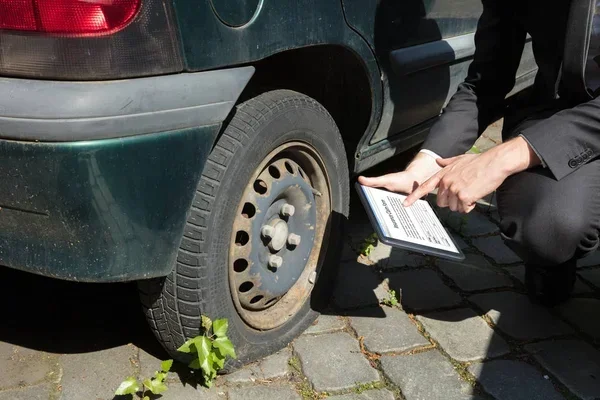
If you have ever walked out to your car only to find a flat tire or a sidewall blowout, you know how frustrating it can be. Tires are expensive, and replacing them quickly adds up. Understanding what your auto insurance policy does and does not cover can save you from an unexpected bill.
In this guide, we break down everything you need to know about tire coverage. We will look at what types of insurance apply, when claims make sense, and how to avoid common pitfalls. By the end, you will know exactly what to expect from your insurer.
Key Takeaways
- Tire coverage varies by policy: Liability insurance alone typically does not cover tire damage.
- Comprehensive coverage helps: It can cover tire damage from non-accident events like theft, vandalism, and weather.
- Collision coverage applies too: If tires are damaged during an accident, collision insurance may pay for replacements.
- Normal wear and tear is excluded: Most insurers will not cover tires that are simply old or worn out.
- Deductibles matter: You will likely need to pay your deductible before insurance kicks in for a tire claim.
- Check your policy details: Always review your specific policy or call your insurance provider to confirm coverage.
- Prevention saves money: Regular tire maintenance and safe driving reduce the risk of tire damage and claims.
📑 Table of Contents
- What Car Insurance Typically Covers
- Does Car Insurance Cover Tires In Different Scenarios?
- When Insurance Will Pay for Tire Replacement
- When Insurance Will Not Pay for Tire Damage
- How to File a Tire Damage Claim
- Tips to Protect Your Tires and Save Money
- How Tire Coverage Compares to Other Vehicle Protection
- Expert Insights on Tire Claims
- Common Mistakes Drivers Make With Tire Claims
- Final Thoughts
What Car Insurance Typically Covers
Before diving into tire-specific coverage, it helps to understand the basics of a standard auto insurance policy. Most policies include several types of coverage, and each one applies to different situations.
Liability Coverage
Liability insurance is the most basic type of coverage. It pays for damage you cause to other people or their property. This includes bodily injury and property damage from an accident you are at fault for. However, liability coverage does not cover damage to your own vehicle, including your tires.
Collision Coverage
Collision coverage pays for damage to your vehicle when you are involved in an accident. This includes collisions with other vehicles, guardrails, or objects. If your tires get damaged during an accident, collision coverage may help pay for repairs or replacements.
Comprehensive Coverage
Comprehensive coverage is the key player when it comes to tire damage outside of accidents. It covers non-collision events such as theft, vandalism, fire, falling objects, and weather damage. If someone slashes your tires or a tree branch falls on your vehicle and damages the tires, comprehensive coverage typically applies.
Uninsured/Underinsured Motorist Coverage
This coverage protects you when the other driver is at fault but does not have enough insurance. If another driver hits your car and damages your tires, this coverage type may help cover the cost.
Does Car Insurance Cover Tires In Different Scenarios?
The answer to this question changes based on what caused the tire damage. Let us look at the most common scenarios drivers face.
Tire Damage From Accidents
If you get into a car accident and your tires are damaged, collision coverage usually steps in. This applies whether you hit a pothole at high speed, crashed into a curb, or were T-boned at an intersection. Your insurer will pay for the tire replacement minus your deductible.
Keep in mind that if the accident was your fault, your own collision coverage handles the claim. If the other driver was at fault, you can file a claim with their liability insurance instead.
Tire Damage From Theft or Vandalism
Have you ever heard of tires being stolen from a parked car? It happens more often than you might think. Comprehensive coverage covers tire theft and vandalism. If someone slashes all four tires in a parking lot, your comprehensive policy should help cover the replacement cost.
Tire Damage From Weather Events
Severe weather can wreck your tires. Hail storms, flooding, and falling tree branches are all covered under comprehensive insurance. For example, if a heavy branch crashes onto your car during a storm and damages the tires, you can file a claim under your comprehensive coverage.
Tire Damage From Road Hazards
Potholes, road debris, and uneven road surfaces are common causes of tire damage. Here is where things get tricky. If you hit a pothole while driving, the damage is often considered a single-vehicle accident. In this case, collision coverage may apply, but only if you have it on your policy.
Many basic policies without collision coverage will not pay for pothole-related tire damage. This is an important detail many drivers overlook when they ask, does car insurance cover tires.
Normal Wear and Tear
Here is the big one your insurer does not cover: normal wear and tear. If your tires are old, the tread is worn down, or they have dry rot, your insurance company will not pay for replacement. Tires are considered maintenance items, just like oil changes and brake pads. Regular tire wear falls under your responsibility as a vehicle owner.
When Insurance Will Pay for Tire Replacement
Understanding when a tire claim is valid can save you time and frustration. Here are the situations where your insurance is most likely to help.
- Accident-related tire damage: Covered under collision coverage if the accident is documented properly.
- Tire theft: Comprehensive coverage applies when tires are stolen from your vehicle.
- Vandalism: Slashed or deliberately damaged tires fall under comprehensive claims.
- Weather-related damage: Storms, falling objects, and natural disasters are comprehensive claims.
- Hit-and-run incidents: If another vehicle damages your tires and flees the scene, uninsured motorist coverage may apply.
It is worth noting that some insurance providers offer road hazard coverage as an add-on or through tire protection plans. This type of coverage specifically addresses damage from nails, screws, and other road debris. Check with your insurance provider to see if this option is available.
When Insurance Will Not Pay for Tire Damage
Not every tire problem qualifies for an insurance claim. Understanding exclusions helps you set realistic expectations.
Wear and Tear Exclusion
Insurance policies explicitly exclude normal wear and tear. If your tires are bald, cracked, or past their expected lifespan, the insurer will deny the claim. This is one of the most common reasons tire claims get rejected.
Gradual Damage
Damage that happens slowly over time is not covered. For example, if your tires develop a slow leak from a small puncture that you ignored for weeks, the resulting damage may not be eligible. Insurance covers sudden and accidental damage, not gradual deterioration.
Missing or Incomplete Coverage
If you only carry liability insurance, your tires are not covered for any type of damage. Liability coverage only pays for damage you cause to others. You need comprehensive and collision coverage on your policy for any tire damage claims to be valid.
Intentional Damage
Insurance does not cover damage you cause intentionally. If you deliberately damage your tires, your claim will be denied, and your policy may be canceled.
How to File a Tire Damage Claim
If you have determined that your policy covers the tire damage, filing a claim is the next step. Here is a simple walkthrough of the process.
- Document the damage: Take clear photos of all damaged tires from multiple angles. Capture the overall vehicle context too.
- Get a police report: For theft or vandalism, file a police report immediately. This strengthens your claim significantly.
- Contact your insurance provider: Call your insurer or use their app to report the claim. Provide all details and documentation.
- Get repair estimates: Visit a tire shop and get a written estimate for the replacement cost. Share this with your insurer.
- Pay your deductible: Before the insurance pays, you must cover your deductible amount. Deductibles typically range from $250 to $1,000.
- Complete the repair: Once the claim is approved, proceed with the tire replacement and submit any additional paperwork your insurer requires.
Keep in mind that filing a claim can affect your car insurance rates. If you have a minor tire claim, it might not be worth it financially. Sometimes paying out of pocket is the smarter choice, especially if the cost is close to your deductible.
Tips to Protect Your Tires and Save Money
Prevention is always better than dealing with a claim. Here are practical steps to keep your tires in good shape and avoid unexpected costs.
Check Tire Pressure Regularly
Underinflated tires wear out faster and are more prone to blowouts. Check your tire pressure at least once a month. Use a reliable tire gauge and match the pressure to your vehicle manufacturer’s recommendations, which you can find on the driver’s side door jamb.
Rotate Your Tires
Rotating your tires every 5,000 to 7,500 miles ensures even wear. This simple maintenance step extends the life of your tires and saves you money in the long run.
Avoid Road Hazards When Possible
Watch for potholes, debris, and uneven road surfaces. Slow down when you spot hazards and steer around them safely. Driving cautiously on rough roads reduces the risk of tire damage significantly.
Invest in Quality Tires
Cheaper tires may save you money upfront, but they often wear out faster and offer less protection. Investing in quality tires from reputable brands can reduce the frequency of replacements and improve your overall safety on the road.
Consider Roadside Assistance Coverage
Many insurance companies offer roadside assistance as an add-on. This coverage can help with flat tires, towing, and other emergencies. It is a small cost that can provide big peace of mind, especially during long road trips.
Review Your Policy Annually
Take time each year to review your auto insurance policy. Make sure your coverage limits and types still meet your needs. If you live in an area with high rates of vandalism or severe weather, consider upgrading to comprehensive coverage if you do not already have it.
How Tire Coverage Compares to Other Vehicle Protection
To put tire coverage in perspective, it helps to compare it with other types of vehicle protection. Here is a quick look at how tire coverage fits into the broader insurance landscape.
| Coverage Type | Covers Tire Damage? | Applies To |
|---|---|---|
| Liability Insurance | No | Damage to others’ property and injuries |
| Collision Coverage | Yes (accident-related) | Damage from crashes and collisions |
| Comprehensive Coverage | Yes (non-accident events) | Theft, vandalism, weather, falling objects |
| Uninsured Motorist Coverage | Yes (if other driver is at fault) | Damage caused by uninsured/underinsured drivers |
| Road Hazard Add-On | Yes (debris and punctures) | Nails, screws, and road debris damage |
This comparison shows that tire coverage is not automatic. You need the right type of coverage on your policy for any tire damage claim to be valid. If you are unsure about what you have, contact your insurance provider directly. They can walk you through your policy details and confirm what is covered.
Expert Insights on Tire Claims
Insurance professionals often advise policyholders to think carefully before filing a tire claim. Here are some insights from the industry.
Small claims may not be worth it. If your deductible is $500 and a tire costs $200 to replace, filing a claim does not make financial sense. You would pay the full cost anyway after the deductible, and the claim could raise your future premiums.
Document everything. Insurance adjusters need clear evidence of the damage. Photos, police reports, and written estimates from tire shops all strengthen your case. The more organized you are, the smoother the claims process will be.
Know your policy limits. Some policies cap the amount they will pay for tire damage. Check your policy documents for any sub-limits related to tires or wheels. Understanding these limits prevents surprises when you file a claim.
Also, keep in mind that car insurance rates can be influenced by your claims history. Filing multiple claims, even for small tire damage, could lead to higher premiums. Weigh the cost of the claim against the potential rate increase before deciding.
Common Mistakes Drivers Make With Tire Claims
Avoid these common pitfalls to make the claims process smoother and protect your wallet.
- Assuming all tire damage is covered: Many drivers file claims without checking their policy first. Always verify coverage before submitting a claim.
- Delaying the claim: Report damage to your insurer as soon as possible. Delays can lead to claim denials.
- Not reading the fine print: Policy documents contain important details about exclusions and limits. Take the time to read them carefully.
- Skipping the police report: For theft or vandalism claims, a police report is almost always required. Do not skip this step.
- Ignoring maintenance records: If your tires were already worn, the insurer may deny the claim. Keep records of regular tire maintenance to prove the damage was not pre-existing.
Final Thoughts
So, does car insurance cover tires? The answer is not a simple yes or no. It depends entirely on your coverage type, the cause of the damage, and the specific terms of your policy. Comprehensive coverage and collision coverage are the two main types that can help with tire damage, while liability insurance alone will not.
Taking the time to understand your auto insurance policy can save you money and stress when unexpected tire damage occurs. Review your coverage annually, document any damage thoroughly, and file claims thoughtfully. If you are shopping for a new policy, consider adding comprehensive and collision coverage to protect your tires and your entire vehicle.
Remember that prevention goes a long way. Regular tire maintenance, safe driving habits, and investing in quality tires all reduce the risk of damage. And if you ever find yourself unsure about what your policy covers, do not hesitate to reach out to your insurance provider. They are there to help you understand your coverage and get you back on the road safely.
Whether you are dealing with a flat tire after a hit-and-run or a set of slashed tires in a parking lot, knowing your coverage gives you the confidence to handle the situation calmly and effectively. Stay informed, stay prepared, and make sure your vehicle protection works for you when you need it most.
Frequently Asked Questions
Will my insurance pay for a flat tire caused by a nail?
It depends on your coverage. If you have comprehensive coverage with a road hazard add-on, the claim may be covered. Without comprehensive coverage, a flat tire from a nail is typically considered wear and tear and will not be covered.
How much does it cost to replace a tire with insurance?
You will pay your deductible first. After that, your insurer covers the remaining cost up to your policy limits. Deductibles usually range from $250 to $1,000, so your out-of-pocket cost depends on your specific deductible amount.
Does full coverage car insurance cover tire damage?
Full coverage typically includes both collision and comprehensive coverage. This means tire damage from accidents, theft, vandalism, and weather events is usually covered. However, normal wear and tear is still excluded.
Can I get temporary insurance to cover new tires?
If you are looking for short-term protection, you can explore temporary car insurance options. Some providers offer flexible policies that can cover tire damage during a specific period. Check with your insurance provider for available options.
Do I need a police report for a tire theft claim?
Yes, most insurance companies require a police report for theft claims. The report serves as official documentation that the incident occurred and strengthens your claim significantly.
Will filing a tire claim raise my insurance rates?
It can. Filing any claim has the potential to affect your premiums, especially if you file multiple claims in a short period. For minor tire damage, it may be more cost-effective to pay out of pocket rather than file a claim.
=== CONCLUSION ===
Does car insurance cover tires? Yes, but only under the right circumstances. Comprehensive coverage and collision coverage are your best allies when it comes to tire damage claims. Understanding your policy, knowing what is covered, and taking preventive steps can make a huge difference. Stay proactive, review your coverage regularly, and never hesitate to contact your insurance provider with questions. Your tires protect your vehicle on every journey, and the right insurance coverage ensures they are protected too.