How Much Does It Cost to Insure a Maserati Every Year
The average cost to insure a Maserati ranges from $2,000 to $5,000 per year, depending on the model, your driving record, and your location. Luxury Italian sports cars like the Maserati carry higher premiums because of expensive parts, repair costs, and theft risk. However, there are several smart strategies you can use to bring your Maserati insurance cost down without sacrificing coverage.
Key Takeaways
- Average Annual Cost: Maserati insurance typically costs between $2,000 and $5,000 per year, with higher-end models costing more.
- Model Matters: The Maserati GranTurismo, Ghibli, and Levant all have different insurance rates based on value and risk.
- Location Impacts Price: Living in a city or high-theft area can significantly increase your premium.
- Coverage Type Is Key: Full coverage with comprehensive and collision will cost more but protects your investment.
- Discounts Help: Bundling policies, maintaining a clean driving record, and installing safety features can lower your rates.
- Compare Quotes: Shopping around among insurers can save you hundreds of dollars annually on luxury car insurance.
📑 Table of Contents
- How Much Does It Cost to Insure a Maserati Every Year?
- Average Maserati Insurance Costs by Model
- Factors That Affect Your Maserati Insurance Rate
- Tips to Lower Your Maserati Insurance Premium
- How Maserati Insurance Compares to Other Luxury Cars
- What Does Maserati Insurance Typically Cover?
- Common Mistakes People Make When Insuring a Maserati
- Final Thoughts on Maserati Insurance Costs
How Much Does It Cost to Insure a Maserati Every Year?
If you have ever wondered about the Maserati insurance cost, you are not alone. These stunning Italian machines turn heads wherever they go. But that beauty comes with a price tag that goes beyond the sticker price. Insuring a Maserati is a completely different experience than insuring a everyday sedan or SUV.
The average annual premium for a Maserati falls between $2,000 and $5,000. However, this range can swing widely based on several factors. Your specific model, driving history, zip code, and coverage choices all play a role. A brand-new Maserati GranTurismo will cost far more to insure than an older Ghibli. Understanding these variables helps you plan your budget and avoid surprises.
Let us break down everything you need to know about how much it costs to insure a Maserati every year. By the end of this guide, you will have a clear picture of what to expect and how to save money.
Why Is Maserati Insurance So Expensive?
Maseratis are luxury Italian sports cars. They are fast, stylish, and expensive to repair. Insurance companies look at many factors when setting your rate. Here are the main reasons premiums for Maseratis tend to be high:
- High Repair Costs: Maserati parts are imported and often custom-made. A simple bumper repair can cost thousands of dollars compared to a standard vehicle.
- Expensive Replacement Value: Even older Maseratis hold their value well. Replacing a totaled Maserati costs significantly more than replacing a mainstream car.
- Theft Risk: Luxury cars are prime targets for thieves. Insurers factor in the higher likelihood of theft when setting premiums.
- Performance Driving: Maseratis are built for speed. Insurers associate high-performance vehicles with a greater risk of accidents.
- Low Production Numbers: Fewer mechanics specialize in Maseratis. This scarcity drives up labor and parts costs dramatically.
All of these factors combine to create a higher risk profile for insurers. That risk translates directly into higher premiums. But do not worry. There are ways to manage and even reduce these costs.
Average Maserati Insurance Costs by Model
Not all Maseratis are created equal when it comes to insurance. The model you choose has a big impact on your annual premium. Here is a closer look at what you can expect for popular Maserati models.
| Model | Average Annual Premium | Key Factors |
|---|---|---|
| Maserati Ghibli | $2,000 – $3,500 | Sedan body, lower theft risk than sports cars |
| Maserati Levante | $2,500 – $4,000 | SUV adds weight, higher repair costs |
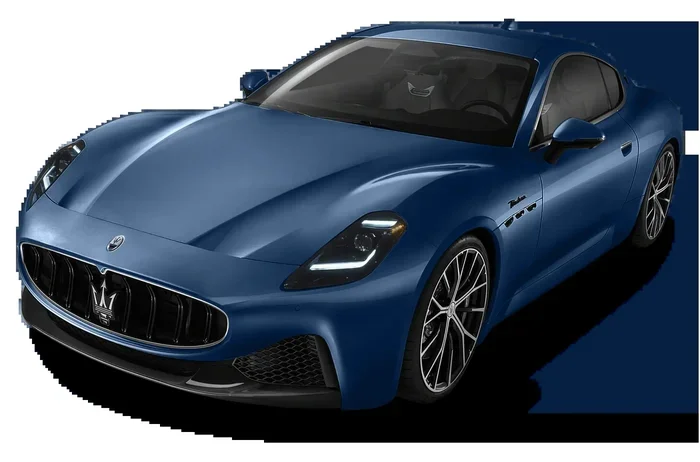
| Maserati GranTurismo | $3,500 – $5,000+ | Sports coupe, high performance, expensive parts |
| Maserati MC20 | $4,000 – $6,000+ | Supercar class, top-tier performance, highest risk |
The Ghibli is the most affordable Maserati to insure. It is a sedan that does not attract the same attention as the sports models. The GranTurismo and MC20 carry the highest premiums. These are pure sports cars that insurers view as high-risk vehicles.
If you are comparing models, keep in mind that the Maserati insurance cost is just one part of the ownership equation. Maintenance, fuel, and repairs also add up quickly with these vehicles.
How Does the Ghibli Compare to Other Models?
The Maserati Ghibli sits in a sweet spot for many buyers. It offers the luxury and brand prestige of a Maserati at a slightly more manageable insurance cost. Because it is a sedan rather than a sports car, some insurers classify it more favorably. This can lead to lower premiums compared to the GranTurismo or MC20.
However, the Ghibli is still a luxury vehicle. It will always cost more to insure than a Honda Accord or Toyota Camry. The difference comes down to parts availability, repair complexity, and the overall value of the car.
Factors That Affect Your Maserati Insurance Rate
Insurance companies do not use a one-size-fits-all approach. Many personal and vehicle-specific factors influence your final premium. Understanding these factors empowers you to make smarter choices.
Your Driving Record
This is the single biggest factor insurers consider. A clean driving record with no accidents or violations will get you the best rates. Even one speeding ticket or at-fault accident can spike your premium by 20% or more. If you have a history of claims, expect to pay toward the higher end of the Maserati insurance cost range.
On the flip side, drivers with excellent records can qualify for significant discounts. Safe driving pays off in a big way when you own a luxury car.
Your Location
Where you live and park your car matters more than you might think. If you live in a densely populated urban area, your rates will be higher. Cities have more traffic, more accidents, and more vehicle theft. Insurance companies also look at local crime rates and weather patterns.
For example, a Maserati parked on the street in a busy city like New York or Los Angeles will cost more to insure than one garaged in a quiet suburban neighborhood. Where possible, park your car in a secure garage to help lower your premium.
Your Age and Gender
Younger drivers, especially those under 25, pay the highest premiums. Insurance companies view them as less experienced and more likely to be involved in accidents. Male drivers also tend to pay slightly more for sports car insurance. These are industry-wide trends that apply to Maseratis as well.
As you gain driving experience and maintain a clean record, your rates will naturally decrease over time.
Coverage Levels and Deductibles
The type and amount of coverage you choose directly impacts your premium. Here is a quick breakdown of common coverage options:
- Liability Coverage: Covers damage you cause to others. This is required by law in most states.
- Collision Coverage: Pays for damage to your Maserati in an accident, regardless of fault.
- Comprehensive Coverage: Covers non-accident damage like theft, vandalism, and weather events.
- Uninsured Motorist Coverage: Protects you if the other driver has no insurance.
Choosing a higher deductible lowers your monthly premium. But it also means you pay more out of pocket if you file a claim. Find a balance that fits your budget and risk tolerance.
How Your Credit Score Plays a Role
In many states, insurers use your credit score as a rating factor. A higher credit score signals financial responsibility. This can lead to lower premiums. A lower credit score may result in higher rates. Improving your credit before shopping for insurance can save you real money on your luxury car insurance premium.
Tips to Lower Your Maserati Insurance Premium
Owning a Maserati does not mean you have to accept sky-high insurance bills. There are several proven strategies to bring your premium down. Here are the most effective tips.
1. Shop Around and Compare Quotes
Never settle for the first quote you receive. Insurance rates vary wildly between companies. Some insurers specialize in luxury vehicles and offer competitive rates for Maseratis. Others may overcharge because they do not understand the market. Get at least three to five quotes before making a decision. The savings can be substantial.
Interestingly, when comparing insurance costs across vehicles, models like the Toyota Highlander or Toyota Tacoma cost far less to insure than a Maserati. This comparison highlights just how much luxury car insurance differs from standard vehicle insurance.
2. Bundle Your Insurance Policies
Most insurance companies offer discounts when you bundle your auto policy with homeowners or renters insurance. Bundling can save you 10% to 25% on your total premium. It is one of the easiest ways to reduce your Maserati insurance cost without sacrificing coverage.
3. Maintain a Clean Driving Record
This cannot be overstated. Avoid speeding tickets, accidents, and traffic violations at all costs. A clean record for three to five years can unlock the best available rates. Some insurers offer safe driver discounts that kick in after a certain period of accident-free driving.
4. Install Anti-Theft and Safety Features
Equip your Maserati with modern safety and anti-theft devices. GPS tracking, alarm systems, and immobilizers can all qualify for discounts. Some insurers also offer reductions for advanced driver-assistance systems (ADAS). Check with your provider to see which features qualify.
5. Consider Usage-Based Insurance
If you do not drive your Maserati every day, usage-based insurance might be a great option. These programs track your driving habits through a device or app. Safe, low-mileage drivers can earn significant discounts. This approach works especially well for luxury cars that are driven occasionally.
6. Pay Annually Instead of Monthly
Many insurers charge a fee for monthly payments. Paying your premium annually avoids these fees and can save you $50 to $100 per year. It also ensures you never miss a payment and risk a lapse in coverage.
How Maserati Insurance Compares to Other Luxury Cars
Curious how a Maserati stacks up against other luxury and sports cars? Here is a general comparison of annual insurance premiums for popular luxury brands:
| Vehicle | Average Annual Premium |
|---|---|
| Maserati Ghibli | $2,000 – $3,500 |
| BMW 3 Series | $1,800 – $3,200 |
| Mercedes-Benz C-Class | $1,900 – $3,400 |
| Audi A4 | $1,700 – $3,000 |
| Lexus ES | $1,400 – $2,500 |
Maseratis generally sit in the higher range of luxury car insurance costs. This is partly because Maserati has a smaller dealer network and fewer certified repair shops. Parts take longer to source, which increases the cost of claims for insurers.
For a different perspective on vehicle insurance costs, models like the Toyota 4Runner are known for being much more affordable to insure. The 4Runner is a rugged SUV with excellent reliability, which insurance companies view favorably.
When you compare a Maserati to a mainstream luxury sedan or SUV, the difference in premiums can be striking. A Maserati GranTurismo might cost nearly double the insurance of a Lexus ES. This gap is driven by performance, repair costs, and the overall risk profile of the vehicle.
What Does Maserati Insurance Typically Cover?
Understanding what your policy covers is essential for making informed decisions. Most standard Maserati insurance policies include the following:
- Bodily Injury Liability: Covers medical expenses for others if you cause an accident.
- Property Damage Liability: Pays for damage you cause to another person’s property.
- Collision Coverage: Repairs your Maserati after an accident, minus your deductible.
- Comprehensive Coverage: Protects against non-collision events like theft, fire, and weather damage.
- Gap Insurance: Covers the difference between your car’s value and what you owe on the loan. This is especially important for new Maseratis, which depreciate quickly in the first few years.
Some insurers also offer roadside assistance and rental car reimbursement as add-ons. These extras provide peace of mind, especially when you are traveling with your Maserati.
Is Gap Insurance Worth It for a Maserati?
Yes. Maseratis depreciate faster than many people expect. In the first year alone, a new Maserati can lose 15% to 20% of its value. If your car is totaled or stolen, gap insurance ensures you are not stuck paying off a loan for a vehicle you no longer have. It is a small cost that can save you thousands of dollars in a worst-case scenario.
Common Mistakes People Make When Insuring a Maserati
Avoid these common pitfalls that can cost you money or leave you underinsured:
- Choosing the Cheapest Policy: The lowest premium is not always the best deal. Make sure the policy covers the full value of your Maserati.
- Underinsuring Your Vehicle: Cutting coverage to save money can backfire. A single accident can cost far more than the savings on your premium.
- Not Shopping Around: Staying with the same insurer for years without comparing quotes means you might be overpaying.
- Ignoring Discounts: Many drivers miss out on available discounts. Always ask your insurer about every possible discount.
- Forgetting to Update Your Policy: If you modify your Maserati or move to a new address, update your policy. Outdated information can lead to claim denials or incorrect premiums.
Take the time to review your policy at least once a year. Your needs and circumstances change, and your insurance should keep up.
Final Thoughts on Maserati Insurance Costs
Owning a Maserati is a dream for many car enthusiasts. The thrill of driving an Italian masterpiece is unmatched. But with that dream comes the responsibility of understanding the insurance cost involved.
The Maserati insurance cost is undeniably higher than insuring a standard vehicle. Annual premiums typically range from $2,000 to $5,000 or more, depending on your model and circumstances. However, with the right strategy, you can manage these costs effectively.
Shop around for quotes, bundle your policies, maintain a clean driving record, and take advantage of every available discount. These steps will help you find the best coverage at the most competitive price. Remember, the goal is not just to find cheap insurance. The goal is to find the right coverage that protects your investment and gives you peace of mind.
A Maserati is more than a car. It is a statement. Make sure your insurance reflects the value and care that goes into owning one of these extraordinary machines.
Frequently Asked Questions
How much does it cost to insure a Maserati every year?
The average annual insurance cost for a Maserati ranges from $2,000 to $5,000. The exact amount depends on your specific model, driving record, location, and coverage choices. Newer and high-performance models like the MC20 will cost more to insure than older or sedan models like the Ghibli.
Why is Maserati insurance so expensive?
Maseratis are luxury Italian sports cars with expensive imported parts and a limited repair network. Insurance companies also factor in higher theft risk and the performance nature of these vehicles. All of these elements combine to create a higher risk profile, which leads to higher premiums.
Can I reduce my Maserati insurance premium?
Yes. You can lower your premium by shopping around for quotes, bundling your insurance policies, maintaining a clean driving record, installing anti-theft devices, and choosing a higher deductible. Every discount you qualify for can make a meaningful difference in your annual cost.
Does the Maserati model affect insurance rates?
Absolutely. The Maserati Ghibli sedan is the most affordable to insure, while the GranTurismo and MC20 sports cars carry the highest premiums. Insurance companies assess each model based on its value, repair costs, theft risk, and performance capabilities.
Is gap insurance necessary for a Maserati?
Gap insurance is highly recommended for Maseratis, especially new ones. These vehicles depreciate quickly, and gap insurance covers the difference between your car’s actual cash value and what you still owe on your loan. This protection can save you thousands of dollars if your car is totaled or stolen.
How does my credit score affect Maserati insurance rates?
In many states, insurers use your credit score as a rating factor. A higher credit score can lead to lower premiums, while a lower score may result in higher rates. Improving your credit before purchasing insurance can help you secure better pricing on your Maserati insurance cost.
=== CONCLUSION ===
How much does it cost to insure a Maserati every year? The answer depends on your model, driving history, location, and coverage choices. Most Maserati owners should budget between $2,000 and $5,000 annually for insurance. While this is higher than insuring a standard vehicle, the right strategies can help you manage and reduce your premium.
Take the time to compare quotes, understand your coverage options, and avoid common insurance mistakes. Your Maserati deserves the best protection, and with the right approach, you can find a policy that balances cost and coverage effectively. Drive your Maserati with confidence, knowing you have made smart, informed choices about your insurance.