How Much Is Car Insurance for a 17-Year-Old per Month
Car insurance for a 17-year-old typically costs between $150 and $400 per month, depending on location, coverage type, and the insurance provider. Adding a teen driver to a parent’s policy is usually the most affordable option, but a 17-year-old can also get their own plan. Good student discounts, safe driver programs, and choosing the right coverage can significantly reduce monthly premiums.
Car insurance for a 17-year-old is one of the biggest expenses new teen drivers and their parents face. The monthly cost can feel shocking, especially when you compare it to adult rates. But understanding how insurance companies price teen policies makes it easier to find affordable options.
Whether you are a parent adding your teen to your existing policy or a 17-year-old looking to get your own plan, knowing what to expect helps you budget and make smart choices. This guide breaks down everything you need to know about monthly car insurance costs for 17-year-olds, from average rates to money-saving tips.
The good news? There are real ways to bring those monthly payments down. Discounts, coverage choices, and smart shopping all play a role. Let us walk through the numbers and options so you can make the best decision for your situation.
Key Takeaways
- Average Cost: Monthly car insurance for a 17-year-old ranges from $150 to $400, with full coverage costing more than minimum liability plans.
- Parent’s Policy Is Cheaper: Adding a 17-year-old to a parent’s existing policy is usually the most budget-friendly option.
- Discounts Help A Lot: Good student discounts, safe driver programs, and defensive driving courses can lower monthly premiums by 10-25%.
- Coverage Type Matters: Liability-only insurance costs less per month than full coverage, but offers less protection.
- Shop Around: Comparing quotes from multiple insurers can save hundreds of dollars per year on teen driver insurance.
- Get Your Own Policy: A 17-year-old can get car insurance in their name, but it will likely cost more than being added to a parent’s plan.
📑 Table of Contents
- What Affects Car Insurance Rates for a 17-Year-Old?
- Average Monthly Cost of Car Insurance for a 17-Year-Old
- Types of Car Insurance Coverage for Teen Drivers
- How to Lower Car Insurance Costs for a 17-Year-Old
- Can a 17-Year-Old Get Their Own Car Insurance Policy?
- Common Mistakes to Avoid When Insuring a 17-Year-Old Driver
- Expert Insights on Teen Car Insurance
- Conclusion
What Affects Car Insurance Rates for a 17-Year-Old?
Insurance companies look at many factors when they set rates for a 17-year-old driver. None of these factors are random. Each one helps the insurer decide how risky it is to cover you. Understanding these factors gives you the power to control what you can and plan for what you cannot.
Your Age and Driving Experience
Being 17 puts you in the highest-risk age group for car insurance. Insurance companies see teen drivers as inexperienced, and statistics back this up. Drivers under 25 have higher accident rates than older drivers, which means higher premiums.
The good news is that your rates will drop as you get older. Every birthday helps. A 17-year-old pays more than an 18-year-old, who pays more than a 25-year-old. This is why many families try to keep their teen on a parent’s policy for as long as possible.
Your Gender
Here is something many people do not expect. Male and female 17-year-olds pay different rates. Statistically, young male drivers get into more accidents than young female drivers. This means a 17-year-old male driver usually pays higher monthly premiums than a 17-year-old female driver.
The gap tends to narrow as drivers get older. By the time you reach your mid-20s, gender plays a much smaller role in your insurance rate. But for now, if you are a young male driver, expect to pay a bit more each month.
Where You Live
Your location has a big impact on your monthly insurance cost. Drivers in busy cities pay more than those in rural areas. This is because city driving means more traffic, more accidents, and more thefts.
States also have different minimum insurance requirements. Some states require more coverage, which raises the base cost. For example, living in a no-fault state can increase your premium compared to a tort state. Your zip code alone can change your rate by hundreds of dollars per year.
Your Vehicle
The car you drive matters a lot. A safe, reliable sedan costs less to insure than a sporty or luxury vehicle. Insurance companies look at the car’s safety ratings, repair costs, and theft risk.
Here are some things that affect how much your car impacts your rate:
- Safety features: Cars with anti-lock brakes, airbags, and backup cameras often qualify for lower rates.
- Vehicle age: Older cars are cheaper to insure because they cost less to repair or replace.
- Engine size: High-performance engines signal higher risk to insurers.
- Theft risk: Cars that are commonly stolen cost more to insure.
Your Driving Record
Even at 17, your driving history matters. A clean driving record keeps your rates lower. Any speeding ticket, at-fault accident, or DUI will cause your monthly premium to spike.
This is why safe driving habits are so important from day one. One bad move on the road can cost you hundreds of extra dollars per year in insurance. If you are a new driver, focus on building a clean record right away.
Average Monthly Cost of Car Insurance for a 17-Year-Old
The big question everyone wants answered: how much does car insurance actually cost for a 17-year-old each month? The answer depends on the type of coverage and your personal situation. Here is a realistic breakdown of what you can expect.
Liability-Only Coverage
Liability-only insurance is the cheapest option. It covers damage you cause to other people and their property. It does not cover your own car if you get into an accident.
For a 17-year-old, liability-only coverage typically costs between $100 and $200 per month. This is the minimum most states require by law. However, liability-only coverage leaves you exposed if your car gets damaged or stolen.
Full Coverage Insurance
Full coverage includes liability, collision, and comprehensive insurance. Collision pays for damage to your car in an accident. Comprehensive covers theft, weather damage, and other non-collision events.
Full coverage for a 17-year-old usually runs between $200 and $400 per month. It is more expensive, but it gives you much better protection. If you have a newer car or a car with a loan, full coverage is often required by your lender.
Adding a Teen to a Parent’s Policy vs. Getting Your Own
Most families save money by adding the 17-year-old to a parent’s existing policy. Being a listed driver on a parent’s plan is almost always cheaper than buying a separate policy. The parent’s driving history and multi-policy discounts bring the cost down.
But there are situations where getting your own policy makes sense. For example, if the teen owns the car outright and the parents want to keep their own rates low. It is also worth noting that if a 17-year-old wants to get car insurance in their own name, they absolutely can.
According to our research, a 17-year-old can get car insurance in their name, but the cost is usually higher than being added to a parent’s policy. The decision depends on your family’s specific situation and budget.
Types of Car Insurance Coverage for Teen Drivers
Not all car insurance is the same. Understanding the different types of coverage helps you choose the right plan at the right price. Here is a simple breakdown of what each type covers and why it matters for a 17-year-old driver.
Liability Insurance
Liability insurance is the foundation of any auto policy. It pays for injuries and property damage you cause to others in an accident. Every state requires some form of liability coverage, though the minimum amounts vary.
For a 17-year-old, liability insurance is the most affordable option. But it only covers the other person’s costs, not yours. Think of it as the bare minimum protection you legally need to drive.
Collision Insurance
Collision insurance pays for damage to your car when you hit another vehicle or object. This is especially important for new drivers who are more likely to get into fender-benders.
Collision coverage comes with a deductible, which is the amount you pay out of pocket before insurance kicks in. Higher deductibles lower your monthly premium. A $1,000 deductible is common and offers a good balance between cost and coverage.
Comprehensive Insurance
Comprehensive coverage handles damage that is not caused by a collision. This includes theft, vandalism, fire, flooding, and falling objects. It also covers windshield damage in most cases.
For a 17-year-old, comprehensive insurance adds peace of mind. Teen drivers face higher risks of theft and vandalism. Adding comprehensive coverage to your policy protects you from unexpected events beyond just accidents.
Uninsured/Underinsured Motorist Coverage
This type of coverage protects you if the other driver in an accident does not have insurance or does not have enough insurance. It is an affordable add-on that can save you thousands in a bad situation.
Many states do not require this coverage, but it is a smart choice for any driver, especially teens. It fills the gap when the other person’s insurance cannot cover your medical bills or car repairs.
How to Lower Car Insurance Costs for a 17-Year-Old
High insurance costs do not have to break the bank. There are many proven strategies to reduce your monthly premium. Some of these take only a few minutes to set up, while others require a bit more effort. But every dollar you save adds up over time.
Take Advantage of Good Student Discounts
Most insurance companies offer a good student discount. If you maintain a B average or higher, you can qualify. This discount typically saves 10 to 25 percent on your monthly premium.
To get this discount, you usually need to provide your report card or proof of enrollment. Keep your grades up and your insurance bills will reflect it. This is one of the easiest ways to save money as a teen driver.
Complete a Defensive Driving Course
Taking a defensive driving course shows insurers you are a responsible driver. Many companies offer discounts of 5 to 15 percent for completing an approved course.
These courses are often available online and can be completed in just a few hours. Some states even require teens to complete a driver’s education course before getting their license. Either way, it is a win-win for safety and savings.
Choose a Higher Deductible
A deductible is what you pay before your insurance kicks in. Choosing a higher deductible lowers your monthly premium. For example, going from a $500 deductible to a $1,000 deductible can save you $20 to $50 per month.
The trade-off is that you pay more out of pocket if you file a claim. Only choose a deductible you can comfortably afford. This strategy works best if you have a clean driving record and do not expect to file many claims.
Shop Around and Compare Quotes
Never accept the first quote you get. Insurance rates vary widely between companies. One insurer might charge $300 per month while another charges $200 for the exact same coverage.
Get at least three to five quotes before you decide. Use online comparison tools to make this process faster. Spending 30 minutes comparing quotes could save you hundreds of dollars every year.
Maintain a Clean Driving Record
Your driving record directly impacts your insurance rate. Avoid speeding tickets, accidents, and traffic violations at all costs. One ticket can increase your monthly premium by 20 percent or more.
Safe driving is not just about staying out of trouble. It is about keeping your insurance costs low for years to come. Build good habits now, and you will thank yourself later.
Can a 17-Year-Old Get Their Own Car Insurance Policy?
The short answer is yes. A 17-year-old can get car insurance in their name. But the process and cost are different from what an adult would experience. Here is what you need to know.
Most insurance companies require the policyholder to be at least 18 years old. However, some insurers allow 17-year-olds to get their own policy if they meet certain requirements. The teen usually needs a job or proof of income to qualify for a standalone policy.
Keep in mind that getting your own policy as a 17-year-old is almost always more expensive than being added to a parent’s plan. The lack of a parent’s driving history and multi-policy discounts drives up the cost. But in some cases, it makes sense financially, especially if the parents have a poor driving record.
If you are considering this path, make sure to compare quotes from multiple insurers. Some companies specialize in insuring young drivers and may offer better rates than the big-name carriers.
Also, remember that car insurance rates for 17-year-olds drop significantly as you gain driving experience. The first few years are the most expensive. But once you turn 18 and build a clean record, your rates will start to come down.
Common Mistakes to Avoid When Insuring a 17-Year-Old Driver
Even well-meaning parents and teens make mistakes when it comes to car insurance. Avoiding these common errors can save you money and headaches.
First, do not choose the cheapest policy without checking the coverage. A low premium with minimal coverage can cost you more in the long run if you get into an accident. Make sure your policy meets your state’s minimum requirements and protects your assets.
Second, do not forget to update your insurer when your teen gets their license. Driving without proper coverage is illegal and risky. Even if you think your teen is just practicing, they need to be listed on your policy.
Third, do not skip discounts. Many families leave money on the table by not asking about available discounts. Good student, defensive driving, and safe vehicle discounts are all easy to qualify for if you know they exist.
Finally, do not assume rates will stay the same forever. Review your policy every year and shop around when your renewal comes up. Insurance markets change, and a better deal may be available now than when you first signed up.
Expert Insights on Teen Car Insurance
Insurance experts agree that the key to managing costs for a 17-year-old driver is planning ahead. Start comparing quotes months before your teen gets their license. This gives you time to find the best rates and coverage options.
Experts also recommend keeping your teen on your policy as long as possible. The multi-car and multi-policy discounts are significant. Once your teen moves out and gets their own car, it may make sense to transfer them to their own policy.
One more tip from the pros: teach your teen about safe driving and insurance together. When young drivers understand how their choices affect their insurance costs, they make better decisions on the road. It is a life lesson that pays off every month.
Conclusion
Car insurance for a 17-year-old per month is a significant expense, but it is one you can manage wisely. The average cost ranges from $150 to $400 per month, depending on your coverage, location, and driving record. Adding your teen to your existing policy is usually the most affordable path.
Take advantage of every discount you qualify for. Good student discounts, defensive driving courses, and safe driving habits all work together to bring your monthly costs down. Compare quotes from multiple insurers to ensure you are getting the best deal.
Remember, this is a temporary situation. Insurance rates for young drivers improve with age and experience. Every year you maintain a clean driving record, your premiums drop. Stay patient, stay safe, and make smart choices today that will save you money for years to come.
Frequently Asked Questions
How much does car insurance for a 17-year-old cost per month on average?
On average, car insurance for a 17-year-old costs between $150 and $400 per month. The exact amount depends on your location, the type of coverage, your vehicle, and your driving record. Full coverage policies cost more than liability-only plans, but they provide better protection.
Can a 17-year-old get their own car insurance policy?
Yes, a 17-year-old can get car insurance in their own name, though it is usually more expensive than being added to a parent’s policy. Some insurers require the teen to have a job or proof of income. Most families save money by adding their teen driver to an existing family policy instead.
What is the cheapest way to insure a 17-year-old driver?
The cheapest way is to add the 17-year-old to a parent’s existing policy. Combine this with good student discounts, defensive driving courses, and a higher deductible to further reduce the monthly cost. Shopping around and comparing quotes from multiple insurers also helps you find the lowest rates.
Do insurance rates go down when a 17-year-old turns 18?
Yes, insurance rates typically drop when a teen turns 18. Turning 25 brings an even bigger reduction in monthly premiums. Maintaining a clean driving record during those years helps keep costs low as you age. Every year of safe driving adds up to lower insurance costs.
Does gender affect car insurance rates for 17-year-olds?
Yes, gender does play a role in teen insurance rates. 17-year-old male drivers typically pay higher premiums than female drivers because statistics show young males have more accidents. The gap narrows significantly as drivers get older and gain more experience on the road.
What discounts are available for 17-year-old drivers?
Common discounts include good student discounts, defensive driving course discounts, and safe driver program rewards. Some insurers also offer discounts for vehicles with safety features like anti-lock brakes and backup cameras. Always ask your insurance provider about every available discount to maximize your savings.
=== INTERNAL LINKS ===
If you want to learn more about teen driver insurance, check out our guide on can a 17-year-old get car insurance in their name for detailed information on getting your own policy.
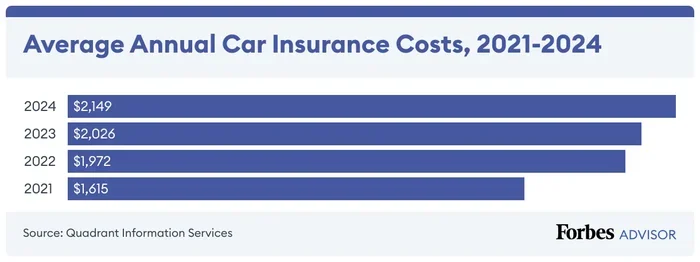
Looking for ways to save on your family’s auto coverage? Our article on are car insurance rates going up covers the latest trends and what to expect in the current market.
Also, if you are wondering about short-term coverage options, read up on can I get temporary car insurance to see if a short-term plan might work for your situation.