How Much Should I Put Down on a Car to Get Approved
Learning how much should I put down on a car is one of the most important steps before you sign any auto loan agreement. A solid down payment lowers your monthly payment, reduces interest charges, and boosts your chances of approval. Most experts recommend putting 10% to 20% of the vehicle price down, but the right number depends on your credit score, budget, and the type of car you buy. This guide breaks down everything you need to know to make the best decision for your wallet.
So you want to buy a car, but you are not sure how much money you should hand over upfront. The question how much should I put down on a car comes up every single day in car dealerships and living rooms across the country. It is one of the biggest financial decisions you will make when purchasing a vehicle. And getting it right can save you thousands of dollars over the life of your loan.
The truth is, there is no one-size-fits-all answer. Your ideal down payment depends on several factors. These include your credit score, your monthly budget, the type of car you want, and the lender you work with. But here is the good news. Once you understand the basics, finding your number becomes much easier. This guide will walk you through everything you need to know to make a smart, confident decision.
Key Takeaways
- A 10% to 20% down payment is the sweet spot for most car buyers looking to get approved and keep payments affordable.
- Your credit score plays a huge role in determining how much you should put down and what interest rate you’ll receive.
- A larger down payment means less interest paid over the life of the loan and a lower risk of being upside down on your car.
- New cars typically require a higher down payment than used cars, but they also come with better loan terms.
- Dealers may push low or zero down offers, but these often lead to higher monthly payments and more interest over time.
- Use a car affordability calculator to find the right down payment amount based on your income and expenses.
- Gap insurance can protect you if your car depreciates faster than your loan balance.
📑 Table of Contents
- Why Your Down Payment Matters So Much
- How Much Should I Put Down on a Car: The General Rules
- Factors That Determine Your Ideal Down Payment
- Common Mistakes People Make with Down Payments
- How to Get Approved for a Car Loan with Any Down Payment
- Special Considerations for Different Buyers
- Final Thoughts: Finding Your Perfect Down Payment
Why Your Down Payment Matters So Much
Many people overlook the importance of a down payment when buying a car. They focus only on the monthly payment or the sticker price. But the amount you put down upfront shapes your entire loan experience. It affects your interest rate, your monthly budget, and even whether you get approved in the first place.
When you put more money down, you borrow less. That means less interest over time. It also shows lenders you are serious and financially stable. A strong car down payment can be the difference between approval and rejection, especially if your credit score is not perfect.
How a Down Payment Affects Your Loan
Let us break this down simply. Imagine you want to buy a car that costs $25,000. If you put $2,500 down (that is 10%), you borrow $22,500. If you put $5,000 down (20%), you borrow $20,000. The difference in interest paid over a five-year loan can be hundreds or even thousands of dollars.
A bigger down payment also reduces your monthly car payment. That frees up room in your budget for other expenses. And it protects you from becoming upside down on your loan. Being upside down means you owe more than the car is worth. This is a situation no one wants to be in.
How Much Should I Put Down on a Car: The General Rules
Now let us get to the heart of the matter. How much should you actually put down? There are some widely accepted guidelines that financial experts and lenders follow. These rules give you a starting point before you dig into your personal situation.
The 10% to 20% Rule
The most common advice you will hear is to put 10% to 20% of the vehicle price down. For a new car, aiming closer to 20% is ideal. For a used car, 10% is often a reasonable starting point. These numbers are not random. They are based on years of lending data and consumer outcomes.
Here is why 20% is the gold standard for new cars. New cars lose value fast. They can depreciate 20% in the first year alone. If you put less than 20% down, you risk owing more than the car is worth almost immediately. That is a dangerous position to be in.
The 20/4/10 Rule
Another popular guideline is the 20/4/10 rule. This means you put 20% down, finance the car for no more than four years, and keep your total monthly vehicle expenses (payment plus insurance and gas) under 10% of your gross monthly income. This rule is a bit stricter, but it leads to much healthier financial outcomes.
Following the 20/4/10 rule means you build equity in your car faster. You pay less interest. And you avoid the trap of stretching payments too long just to get a lower monthly number. It is a strategy that works well for disciplined buyers.
Factors That Determine Your Ideal Down Payment
The general rules give you a starting point, but your personal situation is what really matters. Several factors come into play when deciding how much auto loan down payment is right for you. Let us look at each one closely.
Your Credit Score
Your credit score is one of the biggest factors lenders consider. If you have a high credit score (700 or above), you may qualify for lower interest rates. This gives you more flexibility with your down payment. You might be able to put less money down and still get a great deal.
On the other hand, if your credit score is lower (below 650), lenders see you as a higher risk. They may require a larger down payment to approve your car loan approval. In some cases, they might also charge a higher interest rate. Putting more money down can help you offset that risk and secure better terms.
Quick Tip: Before you visit a dealership, check your credit score for free. Know where you stand. This helps you set realistic expectations and avoid surprises.
Your Monthly Budget
Your monthly budget is another critical factor. How much can you comfortably afford to pay each month? A common mistake is to focus only on the down payment and forget about the long-term cost. A smaller down payment might seem attractive at first, but it leads to higher monthly payments and more interest over time.
Use a car affordability calculator before you decide on a down payment amount. These tools take your income, expenses, and desired loan term to give you a realistic monthly payment estimate. They help you avoid stretching yourself too thin.
New Car vs. Used Car
Whether you are buying a new or used car changes the math. New cars depreciate faster and usually cost more upfront. This means you should aim for a higher down payment, closer to 20%. Used cars have already taken the biggest depreciation hit. A 10% down payment is often sufficient.
Here is a quick comparison to illustrate the difference.
| Factor | New Car | Used Car (3-5 Years Old) |
|---|---|---|
| Recommended Down Payment | 15% to 20% | 10% to 15% |
| Depreciation Risk | High in Year 1 | Lower, Already Depreciated |
| Interest Rates | Lower (typically) | Slightly Higher |
| Loan Term Options | 36 to 72 months | 36 to 60 months |
| Upside-Down Risk | Higher | Lower |
Your Debt-to-Income Ratio
Lenders also look at your debt-to-income ratio (DTI). This is the percentage of your monthly income that goes toward paying debts. A high DTI can make lenders nervous. It suggests you might struggle to take on another monthly payment.
If your DTI is already high, putting more money down can help. It lowers the amount you need to borrow, which lowers your monthly payment. This can improve your chances of car loan approval and help you qualify for better rates.
Common Mistakes People Make with Down Payments
Even well-informed buyers sometimes make mistakes when deciding on a down payment. Being aware of these pitfalls can save you a lot of money and stress. Here are the most common errors people make.
Putting Too Little Down
The biggest mistake is putting too little money down. It feels great to walk out of the dealership with a low upfront cost. But that feeling fades fast when you see your monthly payment. A small down payment means a larger loan, more interest, and a higher risk of being upside down.
Many people fall for zero down payment offers. These sound amazing, but they often come with higher interest rates or longer loan terms. The dealer makes more money, and you end up paying more in the long run.
Putting Too Much Down
Believe it or not, putting too much down can also be a mistake. If you drain your savings to make a massive down payment, you lose your financial safety net. Emergencies happen. Cars break down. Jobs get lost. You do not want to be caught without a cushion.
A good rule of thumb is to never put down more than you can comfortably afford without hurting your emergency fund. Balance is key.
Ignoring the Total Cost of Ownership
Many buyers focus only on the down payment and the monthly loan payment. They forget about insurance, gas, maintenance, and taxes. These costs add up quickly. A car that seems affordable on paper might not be affordable in real life.
Before you commit to any down payment amount, calculate the full total cost of ownership. This gives you a much clearer picture of what the car will actually cost you each month and over the life of ownership.
How to Get Approved for a Car Loan with Any Down Payment
Getting approved for a car loan is not just about the down payment. Lenders look at the full picture. Understanding what they look for can help you prepare and improve your chances of approval, no matter how much you plan to put down.
Get Pre-Approved Before You Visit a Dealership
One of the smartest things you can do is get pre-approval from a bank or credit union before you step onto a lot. Pre-approval tells you exactly how much you can borrow and at what interest rate. It gives you leverage when negotiating with dealers.
When you have pre-approval in hand, you are not at the mercy of the dealership’s finance team. You already know your terms. This puts you in a much stronger position.
Improve Your Credit Score Before Applying
If your credit score is less than ideal, take time to improve it before applying for a loan. Pay down existing debts. Make all payments on time. Dispute any errors on your credit report. Even a small improvement in your score can lead to a significantly better interest rate.
Expert Insight: According to lending experts, raising your credit score by just 20 to 30 points can sometimes save you hundreds of dollars in interest over the life of a car loan. It is absolutely worth the effort.
Consider a Co-Signer if Needed
If you are struggling to get approved on your own, consider asking a trusted family member or friend to co-sign the loan. A co-signer with a strong credit history can help you qualify for better terms and a lower interest rate.
Just remember that a co-signer is taking on real risk. If you miss payments, it affects their credit too. Make sure you are fully committed to making every payment on time.
Special Considerations for Different Buyers
Not every car buyer is in the same situation. Your personal circumstances should guide your down payment decision. Here are some special considerations for different types of buyers.
First-Time Car Buyers
If you are buying a car for the first time, the process can feel overwhelming. You might not have much credit history or savings. In this case, aim for whatever you can reasonably afford. Even 5% or 10% is better than zero. It shows lenders you are serious and gives you some equity from day one.
Look into first-time buyer programs offered by some manufacturers and lenders. These programs often have more flexible requirements and can help you get behind the wheel without a massive down payment.
People with Bad Credit
If you have bad credit, you will likely need to put more money down to get approved. Aim for at least 15% to 20% of the vehicle price. This reduces the lender’s risk and shows you are invested in the purchase.
Be cautious of buy here pay here dealerships. While they may approve you with bad credit, the interest rates are often extremely high. Exhaust all other options first, including credit unions and online lenders.
Leasing vs. Buying
If you are considering a lease instead of buying, the down payment rules are different. Lease down payments are typically lower than loan down payments. A common lease down payment is around 10% to 15% of the vehicle’s value, but some leases require very little upfront.
However, lease down payments (called capitalized cost reductions) are not refundable. If you crash the car or total it in an accident, you do not get that money back. Always compare lease offers carefully and understand what happens to your down payment in different scenarios.
Final Thoughts: Finding Your Perfect Down Payment
So, how much should I put down on a car? The answer is not a single number. It is the amount that fits your budget, protects your financial health, and gets you approved for the loan you want. For most buyers, a down payment between 10% and 20% of the vehicle price strikes the right balance.
Take the time to evaluate your credit score, calculate your budget, and compare offers from multiple lenders. Do not let a dealership rush you into a decision. The more prepared you are, the better the outcome will be.
Remember, the down payment is just the beginning. It sets the tone for your entire ownership experience. Make it count. Use the tips and strategies in this guide to find the perfect number for your situation. Your future self will thank you every month when you make that payment with confidence and ease.
Buying a car is exciting. But it is also a major financial commitment. Treat it that way. Put down the right amount, choose the right loan, and drive away knowing you made a smart, informed decision.
Frequently Asked Questions
What is the best down payment for a car loan?
The best down payment is typically between 10% and 20% of the vehicle price. For new cars, aim closer to 20%. For used cars, 10% is often sufficient. This range helps you keep monthly payments manageable while building equity quickly and avoiding being upside down on your loan.
Can I get approved for a car with no down payment?
Yes, it is possible to get approved with zero down payment, but it comes with trade-offs. You will likely face higher monthly payments, more interest over the life of the loan, and a greater risk of being upside down. A no-down payment option works best for buyers with strong credit scores and stable incomes.
Does a larger down payment guarantee loan approval?
A larger down payment significantly improves your chances of approval, but it does not guarantee it. Lenders also review your credit score, debt-to-income ratio, employment history, and overall financial stability. However, putting more money down definitely strengthens your application and can help you secure better interest rates.
How does my credit score affect the down payment I need?
Your credit score directly impacts how much down payment a lender requires. Buyers with higher credit scores (700+) may qualify for lower down payments and better interest rates. Buyers with lower scores (below 650) often need to put more money down to offset the lender’s perceived risk. Check your score before you start shopping.
Is it better to put more down or finance for a longer term?
Generally, putting more money down is better than financing for a longer term. A larger down payment reduces the total interest you pay and helps you build equity faster. Longer loan terms lower your monthly payment but cost you significantly more in interest over time. The ideal approach is a moderate down payment with a reasonable loan term of three to five years.
Should I use my tax refund as a car down payment?
Using a tax refund as a down payment is a smart move if you do not need the money for emergencies or existing debts. It is essentially free money that reduces your loan balance and interest costs. Just make sure you still have enough savings left to cover unexpected expenses after the purchase.
=== CONCLUSION ===
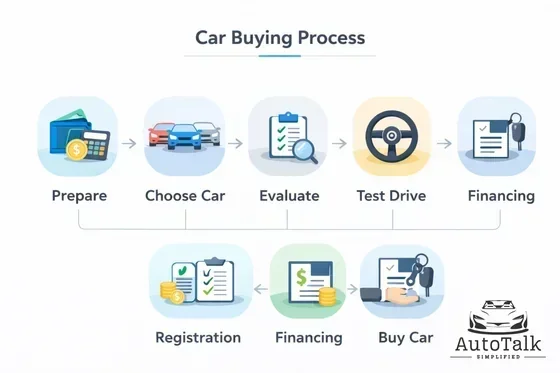
Deciding how much should I put down on a car is one of the most important steps in the car buying process. A well-chosen down payment saves you money, lowers your monthly payments, and increases your chances of approval. Whether you aim for 10%, 15%, or 20%, the key is to make a decision that fits your financial situation and goals.
Do not let anyone rush you into a number that does not feel right. Use the guidelines, tips, and strategies in this article to find your perfect down payment. And remember, the best down payment is the one that keeps you financially healthy while getting you the car you need. Take your time, do your research, and drive away with confidence.